Property Damage: Navigating a Complex Global Issue
Introduction
Property damage, a multifaceted concept encompassing the deterioration or destruction of tangible assets, is a critical aspect of risk management and insurance that impacts individuals, businesses, and societies worldwide. This article aims to delve into the intricacies of property damage, exploring its various dimensions, global implications, economic ramifications, and the role of technology and policy in shaping its landscape. By analyzing these elements, we can gain valuable insights into how communities can better prepare for, mitigate, and recover from property-related losses.
Understanding Property Damage: A Comprehensive Overview
Definition and Core Components
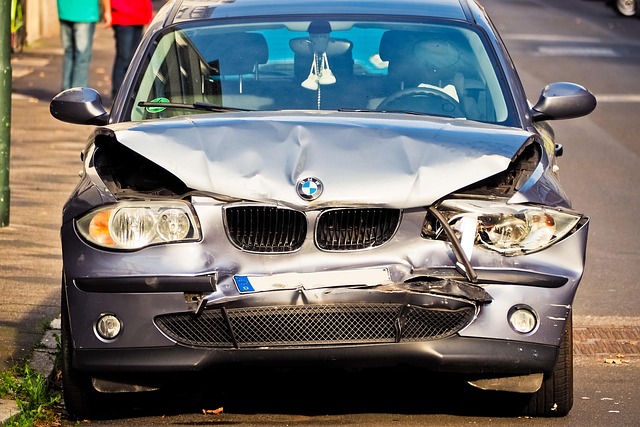
Property damage refers to any intentional or accidental harm caused to real estate, personal belongings, infrastructure, or other tangible assets. It includes a range of incidents such as fires, natural disasters, accidents, vandalism, and malicious destruction. The key components of property damage are:
- Asset Loss: Physical destruction or depreciation of structures, vehicles, equipment, or personal possessions.
- Financial Consequence: The associated costs of repair, replacement, or rebuilding, often covered by insurance policies.
- Disruption: Interference with normal activities, business operations, or daily routines due to the damaged property.
- Emotional and Social Impact: Stress, anxiety, and community disruption caused by the loss or destruction of familiar surroundings.
Historical Context
The concept of property damage has evolved over centuries, shaped by historical events and societal changes. From ancient times, when communities relied on collective efforts for rebuilding after disasters, to the modern era with advanced insurance systems and disaster management protocols, property damage management has been a constant challenge. The Industrial Revolution introduced new challenges, such as urban growth and complex infrastructure, while natural disasters have always been a significant driver of property damage globally.
Global Impact and Trends
International Reach
Property damage is a universal concern, with every country experiencing varying levels of impact. Developed nations often have more sophisticated insurance systems and disaster response mechanisms, while developing countries may face unique challenges related to informal settlements, limited infrastructure, and inadequate coverage. The global nature of property damage is evident in several ways:
- Natural Disasters: Countries in seismic zones, hurricane-prone areas, or floodplains experience recurring property damage from events like earthquakes, hurricanes, and floods.
- Man-made Incidents: Terrorist attacks, industrial accidents, and targeted vandalism can cause widespread property damage in any region.
- Climate Change: Rising temperatures and changing weather patterns are increasing the frequency and intensity of extreme weather events, leading to more property losses globally.
Regional Disparities and Trends
- North America and Europe: These regions have robust insurance industries, advanced warning systems for disasters, and well-established recovery protocols. However, they also face challenges like aging infrastructure and increasing extreme weather events due to climate change.
- Asia-Pacific: Rapid urbanization in this region presents unique property damage challenges, including dense populations, informal settlements, and limited disaster preparedness. Yet, it has also seen significant investments in resilient infrastructure and innovative risk management solutions.
- Africa and Latin America: Developing nations in these regions often struggle with inadequate insurance penetration, informal economy participation, and limited access to resources for recovery and reconstruction. However, they are also embracing technology and community-based disaster preparedness initiatives.
Economic Considerations
Market Dynamics
The property damage sector is a significant contributor to global economic activity, encompassing various industries:
- Insurance: The insurance industry plays a pivotal role in managing property risk by offering policies, assessing claims, and providing financial support for repairs or replacements.
- Construction and Renovation: Damage often triggers construction and renovation activities, creating employment opportunities and stimulating economic growth.
- Disaster Relief Services: Post-damage, temporary housing, cleaning services, and restoration businesses thrive, providing essential support to affected communities.
Investment Patterns
- Private Sector Investment: Businesses invest in property damage mitigation through risk assessment, improved construction techniques, and advanced security systems.
- Government Spending: Public funds are allocated for disaster preparedness, emergency response equipment, and resilient infrastructure development.
- International Aid: In the aftermath of major disasters, international organizations and countries provide aid, contributing to recovery efforts and rebuilding projects.
Economic Impact Assessment
Research suggests that property damage costs worldwide amount to billions of dollars annually. For example:
- A 2021 study by the Global Facility for Disaster Reduction and Recovery (GFDRR) estimated global disaster-related economic losses at USD 345 billion in 2020, with property damage accounting for a significant portion.
- The insurance industry's global property/casualty market size was valued at approximately USD 1.7 trillion in 2022, reflecting the substantial financial exposure related to property damage.
Technological Advancements and Their Impact
Innovations in Damage Assessment
- Drone Technology: Drones equipped with high-resolution cameras and sensors can efficiently survey damaged areas, providing aerial imagery for rapid assessment of property losses.
- Satellite Imagery: Advanced satellite systems offer before-and-after views of affected regions, helping insurance adjusters and disaster management teams assess damage at a large scale.
- AI and Machine Learning: These technologies enable automated analysis of images and data, improving speed and accuracy in damage assessment and claims processing.
Enhancing Disaster Preparedness and Response
- Smart Cities Initiatives: Integrating technology into urban infrastructure allows for real-time monitoring, early warning systems, and efficient disaster response coordination.
- Resilient Building Designs: Advanced construction materials and techniques, such as earthquake-resistant structures and flood-proof buildings, minimize property damage during disasters.
- Digital Insurance Policies: Online platforms offer personalized insurance plans, making it easier for individuals and businesses to access coverage and file claims digitally.
Future Potential and Challenges
The integration of technology in property damage management presents both opportunities and challenges:
- Opportunities: Improved data analytics can predict high-risk areas, enabling proactive measures. Blockchain technology can enhance insurance claim transparency and security.
- Challenges: Data privacy concerns arise with the increasing collection and sharing of sensitive information. Ensuring equitable access to technology for all communities remains a critical issue.
Policy and Regulation: Shaping the Landscape
Global and Regional Frameworks
- United Nations (UN) Conventions: Various UN initiatives, such as the Hyogo Framework for Action and the Paris Agreement, provide guidelines for disaster risk reduction and climate change adaptation, indirectly addressing property damage mitigation.
- World Bank Initiatives: The World Bank supports vulnerable countries in building resilience through projects like the Global Risk Assessment and the Catastrophe Risk Insurance Facility.
- Regional Organizations: Regional bodies like the European Union (EU) and Association of Southeast Asian Nations (ASEAN) have developed policies for disaster management and climate change adaptation, including property damage considerations.
National Level Policies
- Building Codes and Regulations: Governments enforce building codes to ensure structures meet safety standards, reducing potential damage during disasters.
- Insurance Mandates: Some countries mandate certain types of insurance coverage, such as flood or earthquake insurance, to protect citizens from property loss.
- Disaster Preparedness Laws: Legislation may require local governments to develop emergency response plans, conduct regular drills, and maintain emergency supplies.
Influencing Industry Practices
Policymakers influence private sector behavior through incentives, regulations, and industry standards:
- Tax benefits and subsidies encourage businesses to adopt risk management practices and invest in resilient infrastructure.
- Regulatory bodies set guidelines for insurance coverage, claim settlement processes, and fair pricing, ensuring consumer protection.
- Industry associations promote best practices, knowledge sharing, and standardization of damage assessment procedures.
Challenges and Criticisms: Overcoming Barriers
Main Challenges
- Inequitable Access to Resources: Socioeconomic disparities lead to unequal property damage resilience, with vulnerable communities often bearing the brunt of disasters.
- Limited Data and Research: Inadequate data collection and research hinder evidence-based decision-making for effective property damage mitigation strategies.
- Complex Insurance Systems: The complexity of insurance policies, claims processes, and coverage exclusions can be a barrier to accessing compensation for victims.
- Rapid Urbanization: Unplanned urban growth contributes to dense, vulnerable settlements, exacerbating the impact of property damage events.
Criticisms of Existing Approaches
- Lack of Integration: Siloed approaches by different government departments and agencies hinder comprehensive disaster management and property damage response.
- Insufficient Investment: Insufficient funding for disaster preparedness, resilience infrastructure, and research limits long-term solutions.
- Inadequate Public Awareness: Low public knowledge about disaster risks and recovery procedures can lead to inadequate individual and community preparedness.
Strategies for Improvement
- Equitable Access to Resources: Governments should prioritize investments in vulnerable areas, offering incentives for resilient infrastructure development and risk mitigation measures.
- Enhanced Data Collection: Standardized data collection methods and research collaborations can improve understanding of property damage trends and risks.
- Simplifying Insurance Processes: Streamlining claims procedures, promoting transparent communication, and simplifying policy language can enhance access to insurance benefits.
- Community Engagement: Encouraging public participation in disaster preparedness planning and community-based initiatives fosters collective resilience.
Case Studies: Successful Applications and Lessons Learned
Case Study 1: Japan's Resilient Infrastructure
Japan, frequently exposed to earthquakes and typhoons, has implemented robust property damage mitigation strategies. The country's strict building codes mandate advanced structural designs, including seismic reinforcement and flood-proof measures. This has resulted in significantly reduced fatalities and property losses during major events like the Great Hanshin Earthquake (1995) and Typhoon Jebi (2018).
Lessons Learned:
- Stringent building regulations and standards can substantially minimize property damage and loss of life.
- Continuous investment in resilient infrastructure is crucial for long-term disaster risk reduction.
Case Study 2: The Netherlands' Delta Works
The Dutch government has engineered an extensive system of dikes, dams, and storm surge barriers, known as the Delta Works, to protect its low-lying regions from floods. This multi-billion-dollar project has successfully prevented significant property damage during extreme weather events, demonstrating the power of technological solutions in disaster risk management.
Lessons Learned:
- Integrated water management systems can effectively mitigate flood risks and protect valuable assets.
- Long-term planning and substantial investment pay dividends in ensuring community safety and preserving property value.
Case Study 3: Community-Driven Recovery in Puerto Rico
After Hurricane Maria (2017), Puerto Rico's community-based recovery efforts demonstrated the power of local knowledge and engagement. Neighborhoods organized to clear debris, establish temporary shelters, and coordinate rebuilding efforts. This bottom-up approach complemented government initiatives, ensuring a more inclusive and effective recovery process.
Lessons Learned:
- Community resilience and participation are vital for successful post-disaster recovery.
- Local knowledge and collaboration can fill gaps in traditional disaster response structures.
Future Prospects: Emerging Trends and Opportunities
Growth Areas
- Digital Transformation: The digital revolution offers opportunities to streamline property damage assessment, claims processing, and insurance distribution through AI, blockchain, and IoT applications.
- Sustainable Building Practices: Increasing emphasis on green building standards and sustainable design will lead to more resilient structures, reducing environmental impact and long-term maintenance costs.
- Microinsurance: Targeted microinsurance products can provide affordable coverage for low-income communities, ensuring access to financial support during property damage events.
Emerging Trends
- Smart Cities and Digital Infrastructure: Urban areas will continue to embrace smart city technologies, enhancing real-time monitoring, early warning systems, and efficient disaster response coordination.
- Climate Change Adaptation: As climate change intensifies, countries will focus on adapting their built environments, infrastructure, and policies to reduce vulnerability and build resilience.
- Disaster Finance Mechanisms: Innovative financial tools, such as catastrophe bonds and parametric insurance, offer rapid funding for recovery efforts, ensuring timely support for affected communities.
Strategic Considerations
- Data Analytics and AI Integration: Advanced analytics will be crucial for predicting risks, optimizing resource allocation, and improving decision-making across all sectors involved in property damage management.
- Public-Private Partnerships (PPPs): Collaborating with the private sector can leverage expertise, resources, and innovative solutions to enhance disaster risk reduction and recovery efforts.
- Community Engagement and Education: Empowering communities through education, training, and participation ensures a more robust and resilient society, capable of responding effectively to property damage events.
Conclusion: Navigating a Complex Future
Property damage is an inescapable aspect of the human experience, shaped by natural forces, man-made incidents, and evolving global conditions. As our world becomes increasingly interconnected and vulnerable to environmental changes, effective property damage management will be critical for safeguarding communities, economies, and cultural heritage. This article has explored various dimensions of property damage, highlighting its historical context, global impact, economic considerations, technological advancements, policy frameworks, challenges, and successful case studies.
Looking ahead, the future of property damage management holds both opportunities and complexities. Embracing technology, fostering community resilience, and implementing evidence-based policies will be essential to navigate this challenging landscape. By learning from past experiences and adapting to emerging trends, we can build a more sustainable and resilient global community capable of withstanding the tests of time and nature.
FAQ Section: Addressing Common Concerns
Q: How does climate change contribute to property damage?
A: Climate change exacerbates various natural hazards, such as increasing the intensity of hurricanes, prolonging wildfire seasons, intensifying rainfall leading to floods, and raising sea levels, all of which heighten the risk of property damage globally.
Q: What role does insurance play in managing property damage?
A: Insurance provides financial protection against property loss or damage by offering policies tailored to specific risks. It encourages risk mitigation measures, facilitates faster recovery through claims processing, and contributes to overall disaster risk reduction efforts.
Q: How can individuals prepare for potential property damage?
A: Individuals can take several steps, including creating emergency kits, developing evacuation plans, ensuring adequate insurance coverage, maintaining home maintenance, securing valuable possessions, and staying informed about local disaster preparedness guidelines.
Q: What are some innovative technologies in property damage assessment?
A: Drones with high-res cameras, satellite imagery analysis, AI-driven image recognition, and IoT sensors for real-time monitoring are among the innovative technologies revolutionizing property damage assessment, offering speed, efficiency, and accuracy.
Q: How can governments improve disaster preparedness at a national level?
A: Governments can enhance disaster preparedness by implementing building codes, mandating insurance coverage, investing in resilient infrastructure, conducting regular drills and exercises, maintaining emergency response plans, and fostering public awareness through education programs.